Imagine this…
You want to transfer ₦50,000 to someone. You open your banking app, enter the account number, type the amount, and press SEND.
A few seconds later, you realise something is wrong.
You sent the money to the wrong account! 😭
Your heart skips. You start sweating. You check the transaction again and again, hoping you made a mistake while checking.
But no… the money has actually gone to another person's account.
At this point, some people will start shouting. Others will begin praying. Some will call the person they intended to pay, while others will simply conclude that their money is gone forever.
But hold on!
Sending money to the wrong account doesn't automatically mean your money is lost forever. There are steps you can take to try to recover it, especially if you report the mistake quickly.
Whether you use OPay, PalmPay, Moniepoint or a traditional Nigerian bank, please read this carefully. You might need this information one day, or it might help someone close to you.
Let's break it down.
💰 FIRST, CAN YOU ACTUALLY RECOVER MONEY SENT TO THE WRONG ACCOUNT?
Yes, recovery is possible in some cases, but it is not guaranteed.
Your chances may depend on several things:
- How quickly you report the wrong transfer.
- Whether the money is still in the receiving account.
- Whether the recipient agrees to return it.
- The financial institution involved and its recovery procedures.
- Whether further investigation or legal action becomes necessary.
One important thing to understand is that a completed transfer usually cannot simply be cancelled with one click.
Once the money has entered another person's account, the financial institutions involved may need to investigate, contact the recipient and follow the appropriate procedures before any refund can happen.
So, what should you do immediately?
🚨 STEP 1: REPORT THE WRONG TRANSFER IMMEDIATELY
The moment you discover the mistake, contact the customer support team of the app or bank you used to send the money.
Don't wait until tomorrow. Don't spend three days hoping the recipient will discover the money and return it.
Report it as soon as possible.
Be ready to provide the following information:
✅ The transaction reference number or transaction ID.
✅ The exact amount you transferred.
✅ The date and time of the transaction.
✅ The incorrect account number and recipient details.
✅ Your own account details.
✅ Your transaction receipt or screenshot, if requested.
Keep your complaint reference number and any messages you receive from customer support. These can help when following up on the case.
Important: Use the app's official support channel or verified contact details. Never give anyone your PIN, password or OTP because they claim they want to help you recover your money.
🔄 STEP 2: REQUEST A TRANSFER RECALL OR REVERSAL
When contacting support, clearly explain that you sent money to the wrong account and want to initiate a recovery process.
Depending on the circumstances, your financial institution may contact the receiving institution, investigate the transaction and request that the recipient return the funds.
If the money is still available, the receiving institution may be able to take appropriate steps to preserve it while the complaint is investigated.
However, don't assume the money will be frozen automatically or refunded immediately. The outcome depends on the case and the applicable procedures.
Now, let's look at what you can do on the three popular platforms.
📱 HOW TO RETRIEVE MONEY SENT TO THE WRONG ACCOUNT ON OPay
If you mistakenly sent money to the wrong OPay account, here's what to do:
- Open your OPay app.
- Look for Help & Support.
- Find the option relating to transfer issues or money sent to the wrong account.
- Follow the available instructions to submit your complaint.
- Provide your transaction reference, amount, date, time and incorrect recipient details.
If you cannot find the exact option in your version of the app, contact OPay through its official support channel and explain the situation.
What happens after you report it?
OPay may investigate the transaction and contact the recipient or follow the applicable recovery procedure.
If the funds are still available, that may improve your chances of getting them back. If the recipient has already withdrawn or spent the money, recovery can become more difficult.
The original article gives an indicative timeframe of 24 hours to 5 working days for OPay cases, but this is not a guaranteed deadline. Some cases may take longer.
📱 HOW TO RETRIEVE MONEY SENT TO THE WRONG ACCOUNT ON PalmPay
PalmPay users can also report mistaken transfers.
Try the following steps:
- Open your PalmPay app.
- Tap Me.
- Open the Help Center.
- Look for Transfer Problems or the relevant wrong-transfer complaint option.
- Submit the transaction details and follow the instructions provided.
If the menu options have changed, use PalmPay's official customer support channel instead.
PalmPay may verify the transaction, contact the recipient and follow the appropriate process to request a refund.
Please understand that reporting a wrong transfer does not guarantee an automatic reversal. You may need to follow up with customer support until the complaint is resolved.
The original article gives an indicative timeframe of 1–7 working days, but actual resolution time can vary.
📱 HOW TO RETRIEVE MONEY SENT TO THE WRONG ACCOUNT ON MONIEPOINT
If you're using Moniepoint and accidentally transfer money to the wrong account, don't keep quiet about it.
Take these steps:
- Contact Moniepoint through its official customer support channel as soon as possible.
- Explain that the transfer was sent to the wrong recipient.
- Provide your transaction ID or reference number.
- State the amount transferred and the date and time.
- Supply the incorrect recipient's account details and any supporting transaction evidence requested.
Keep the complaint reference and follow up if you don't receive an update.
If the recipient is a Moniepoint customer or POS agent, the details of the transaction may help the institution investigate the case. However, being a Moniepoint recipient does not guarantee faster recovery.
The original article gives an indicative timeframe of 2–10 working days for Moniepoint cases. This is not an official guarantee, and complicated cases may take longer.
😟 WHAT IF THE PERSON REFUSES TO RETURN YOUR MONEY?
This is where things can become frustrating.
Imagine sending ₦100,000 to the wrong account, reporting it immediately, and then discovering that the recipient has received your money but refuses to cooperate.
What should you do?
First, don't threaten the person, publish their private information online or attempt to access their account yourself.
Instead:
1. Escalate the complaint.
Contact your bank or fintech again, provide your complaint reference number and ask for the case to be escalated.
2. Make a formal complaint.
Keep copies of your transfer receipt, complaint messages and any communication with the recipient.
3. Ask about further escalation.
Depending on the institution involved, you may be able to escalate an unresolved complaint to the appropriate financial regulator or complaints channel.
4. Consider legal advice if necessary.
If the amount is significant or the recipient deliberately refuses to return the money, seek appropriate legal advice about your options.
Money received by mistake can raise legal issues, but the exact legal position depends on the circumstances. Don't assume that a bank can immediately take money from another person's account without the required authority or procedure.
⏳ HOW LONG DOES IT TAKE TO GET YOUR MONEY BACK?
There is no single timeframe that applies to every wrong transfer.
Here are the indicative estimates provided in the original article:
| Situation | Possible timeframe |
|---|---|
| Reported quickly, with funds still available | 24–72 hours in some cases |
| Recipient has already withdrawn the money | Several days to weeks, or longer |
| Further legal action is necessary | Weeks to months, potentially longer |
These are illustrative estimates, not guaranteed processing times for every bank or fintech.
The most important thing is to report the issue quickly and keep following up through official channels.
❓ WHAT IF THE ACCOUNT NUMBER YOU ENTERED DOESN'T EXIST?
This is a different situation.
If the account details are invalid and the transfer cannot be completed, the transaction may fail or the funds may be returned automatically.
However, don't assume that every failed-looking transaction will reverse within a particular number of hours.
Check the transaction status, contact your financial institution if the money has been debited, and request an investigation if the funds do not return.
❓ WHAT IF THE ACCOUNT NUMBER EXISTS, BUT IT BELONGS TO ANOTHER PERSON?
Unfortunately, this is the more complicated situation.
The transfer may have been completed successfully, even though you sent the money to the wrong person.
You will generally need to report the mistake and follow the institution's recovery procedure.
The sooner you report it, the better your chances may be, particularly if the funds are still available.
❓ CAN YOUR BANK IDENTIFY THE PERSON WHO RECEIVED YOUR MONEY?
Your financial institution can generally investigate the receiving account through the appropriate channels.
However, privacy rules may prevent it from giving you the recipient's personal information directly.
Let the bank or fintech handle the investigation rather than trying to obtain private account information yourself.
🛡️ HOW TO AVOID SENDING MONEY TO THE WRONG ACCOUNT AGAIN
Sometimes, a few seconds of carelessness can cause days or weeks of stress.
Here are four habits that can save you trouble:
1. Always confirm the account name.
Before pressing the transfer button, check that the displayed recipient's name matches the person or business you intend to pay.
If the name doesn't match, stop and investigate.
2. Send a small test amount for large or unfamiliar transfers.
If you're paying a new recipient, consider sending a small amount first and confirming receipt before sending the balance.
3. Don't rush your transfers.
Many mistakes happen because people are distracted, in a hurry or trying to complete a transaction while doing something else.
Take a few seconds to verify the details.
4. Save frequently used beneficiaries.
Saving verified recipients can reduce the risk of repeatedly typing the wrong account number.
Just make sure you verify the details before saving them.
🔥 LET'S TALK! HAS THIS EVER HAPPENED TO YOU?
Now, I want to hear from members of this community.
Have you ever mistakenly transferred money to the wrong account using OPay, PalmPay, Moniepoint or your bank app?
Maybe you recovered the money after contacting customer support. Maybe the recipient returned it voluntarily. Or maybe you're still chasing the money till today!
Please share your experience in the comments. Your story could help someone avoid making the same mistake or show another person what to do when it happens.
👇 Tell us:
1. Which platform did you use? OPay, PalmPay, Moniepoint or another bank?
2. How much did you mistakenly send? You don't have to disclose the exact amount if you're uncomfortable.
3. Were you able to recover the money? If yes, what steps helped you? If not, what happened?
Let's learn from one another. And please, never share your PIN, OTP, password or full account details in the comments.
A few days ago, I was talking with someone who works remotely, and his biggest complaint wasn't NEPA.
It was internet.
One minute he's on a Zoom call, the next minute he's reconnecting. Videos buffering. Downloads taking forever. Deadlines getting delayed because of poor network.
That's when MTN FibreX came up in the conversation.
Some people are already calling it one of the best internet solutions in Nigeria right now. Others say it's still limited because it hasn't reached everywhere yet.
So I decided to dig into it, and here's what I found. 👇
First, What Exactly Is MTN FibreX?
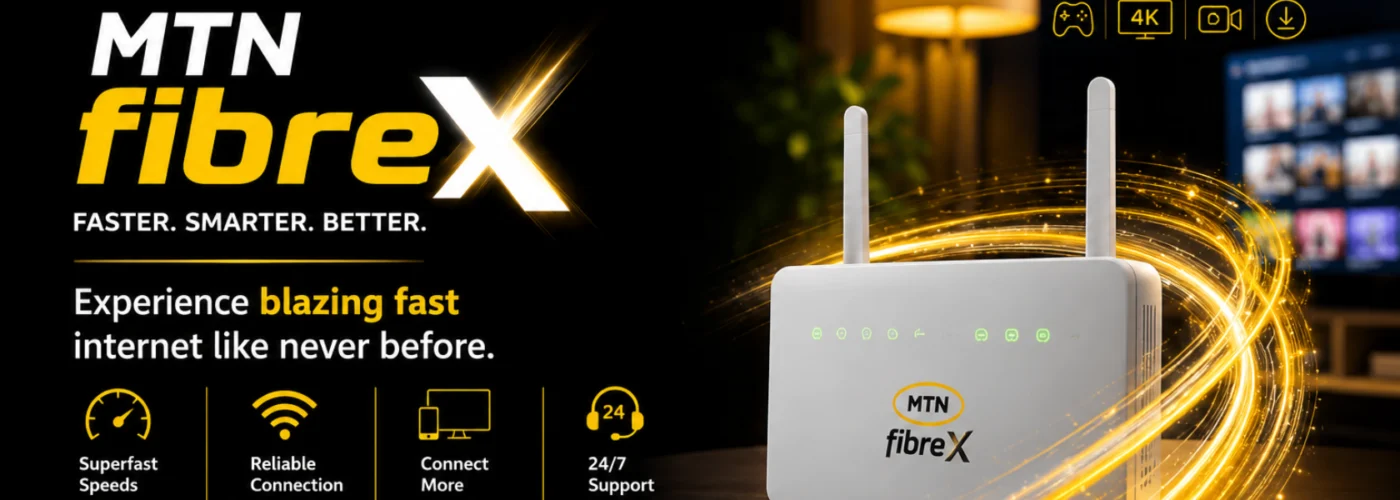
MTN FibreX is MTN's fibre-optic internet service for homes and businesses.
Unlike regular mobile data that depends on nearby network towers, FibreX brings internet directly to your home or office through fibre-optic cables.
The result?
✅ Faster speeds
✅ More stable connection
✅ Lower latency
✅ Better performance during peak hours
✅ Support for multiple devices at the same time
It's designed for people who stream, work remotely, attend online classes, game, create content, or run businesses that depend heavily on the internet.
Where Is MTN FibreX Available?
This is the part many people care about.
The service is NOT available everywhere in Nigeria yet.
According to available coverage information, FibreX currently covers selected locations in:
- Abuja (FCT)
- Lagos
- Ogun
- Oyo
- Rivers
- Kano
- Kaduna
- Kwara
And MTN keeps expanding into more estates, neighbourhoods, and cities. Availability depends on your exact address, not just your state.
For example:
Abuja
Some covered areas include:
- Jabi
- Jahi
- Life Camp
- Dawaki
- Kubwa
- Kado
- Mbora
- Wuse II
- Gwarinpa
Lagos
Coverage exists across many estates, business districts, and residential areas.
Other States
Selected locations in Ogun, Oyo, Rivers, Kaduna, Kano, and Kwara also have FibreX access, with more expansion ongoing.
Why Are People Interested in FibreX?
Imagine a household where:
- Dad is on a Zoom meeting.
- Mum is watching Netflix.
- One child is on YouTube.
- Another is playing online games.
- CCTV cameras are connected.
- Everyone is using WiFi at the same time.
Normally, that's where many internet services start struggling.
FibreX was built for this kind of heavy usage.
It's suitable for:
- Homes & families
- Small businesses
- Schools
- Hotels
- Hospitals
- Churches
- Cyber cafés
- Content creators
- Freelancers
- Remote workers
Current MTN FibreX Plans
From MTN's official information, FibreX currently offers:
| Plan | Speed | Monthly Price |
|---|---|---|
| Basic | 50 Mbps | ₦30,000 |
| Standard | 100 Mbps | ₦45,000 |
| Advanced | 200 Mbps | ₦70,000 |
| Premium | 300 Mbps | ₦100,000 |
| Prestige | 1 Gbps | ₦200,000 |
All plans come with 30-day validity.
What Do You Get?
According to MTN, new FibreX customers receive:
✅ Free installation
✅ Free-to-use router
✅ Dedicated customer support
✅ Unlimited internet plans
MTN also states that its unlimited FibreX plans do not have a Fair Usage Policy (FUP) and are not throttled during peak hours.
How Installation Works
If FibreX is available in your area, the process usually goes like this:
- Address verification
- Site survey
- Fibre cable installation
- Router setup
- Internet activation
- Speed testing
Installation speed can vary depending on your location and infrastructure readiness. Some users report quick installations, while others say it can take longer depending on demand and area coverage.
How Do You Check If Your Area Is Covered?
You'll usually need:
- State
- City
- Estate/Area
- Street Name
- House Number
If your address qualifies, MTN can proceed with installation. MTN also provides a FibreX coverage checker for customers.
Pros of MTN FibreX
From everything I've read, the biggest advantages are:
✔ Very fast internet
✔ Stable connection
✔ Unlimited plans
✔ Supports many devices simultaneously
✔ Excellent for streaming
✔ Great for gaming
✔ Suitable for remote work
✔ Better performance than typical mobile broadband during busy periods
The Downsides
No service is perfect.
Current limitations include:
❌ Not available nationwide
❌ Some neighbourhoods still have no fibre infrastructure
❌ Installation depends on whether MTN has already deployed fibre cables in your area
❌ Some users report occasional downtime or installation delays, depending on location and support experience.
My Verdict
If FibreX is available in your area, it looks like one of the strongest home internet options currently available in Nigeria.
The combination of fibre technology, unlimited plans, free installation, and high speeds makes it attractive for anyone who depends heavily on the internet.
The biggest challenge right now is simply coverage.
Many Nigerians still can't get it because FibreX hasn't reached their street yet.
But where it's available, many users consider it a major upgrade from traditional mobile internet solutions.
Community Discussion 👇
I want to hear real-life experiences, not advertisements.
Have you used MTN FibreX before?
- Which city are you in?
- What speed plan are you using?
- Is it truly stable?
- Any downtime?
- How does it compare with Starlink, Spectranet, Smile, Airtel, or normal MTN data?
- If FibreX isn't available in your area, what internet service are you currently using?
Drop your experience below. Someone in this community might be making an internet decision this week and your comment could save them money (or frustration).

I just crossed 100 watch hours and I’m pumped!! 🔥
It might not be 4,000 yet, but hitting this number feels like I’m gaining real traction. What made a difference this month:
🎯 Longer Videos – I experimented with a few 8–10 minute videos instead of my usual 3-4 min ones, and they’ve been performing better!
🔁 Playlists - I created themed playlists and noticed people watching more than one video in a row. Game-changer!
📊 Better Titles - I started using curiosity-based titles that make people want to click and watch longer.
I know I still have a long way to go, but celebrating small wins keeps me going. Next goal: 250 watch hours 🚀
How many watch hours have you hit so far? Let’s share and celebrate our progress together!

Let’s have a real conversation for a second…
If I told you that some people are making serious money on YouTube - without showing their face, without speaking, and sometimes without even editing videos themselves…
Would you believe it?
Because honestly, when most people hear “start a YouTube channel,” the first thing that comes to mind is:
- “I don’t like camera”
- “I’m not confident speaking”
- “I don’t have editing skills”
- “I don’t have money to hire editors”
Sound familiar?
That’s exactly where most people stop.
But here’s what’s interesting…
Inside this space, there are people quietly building faceless YouTube channels that pull in $600 to $800 PER DAY - just by following a simple system.
No hype. Just leverage.
The Real Problem (Why Most People Never Start)
Let’s be honest…
Starting this kind of YouTube channel sounds simple until you think about everything involved:
- Coming up with video ideas
- Writing scripts that don’t bore people
- Finding visuals
- Editing everything together
- Creating thumbnails
- Understanding keywords & SEO
Then someone tells you:
“Just hire someone…”
Next thing - you’re hearing $200 - $300 per video
At that point, most people check out.
But What If You Could Do Everything From Your Phone in 10 Minutes?
This is where things get interesting.
There are now tools that can take just a title or idea and turn it into a full video:
- Script ✅
- Voiceover (human-like) ✅
- Background music ✅
- Stock footage ✅
- Subtitles ✅
All done automatically.
So instead of needing a team…
You just need a good idea and a system.
Let’s Break Down The Simple 3-Step System
Step 1: Pick a Niche (This Part Matters More Than You Think)
Don’t treat YouTube like a hobby - treat it like a business.
Some niches pay WAY more than others.
Here are examples of high-paying niches (CPM = what you earn per 1,000 views):
- Finance & Investment: $20 - $50
- Business & Entrepreneurship: $15 - $30
- Tech Reviews: $15 - $20
- Luxury & Lifestyle: $10 - $20
- Legal Advice: $20 - $45
- Health & Wellness: $10 - $20
- Real Estate: $15 - $25
- Beauty & Skincare: $8 - $18
- Travel: $8 - $16
Now think about this…
If your niche pays $10 per 1,000 views, and your video gets 80,000 views in a day…
That’s roughly $800/day
And yes - there are faceless channels already doing this consistently.
💬 Quick one…
If you had to pick right now - which niche would you enter and why?
(Drop it below, no overthinking 👇)
Step 2: Create Titles That People Actually Click
This is where most people get it wrong.
Your video can be amazing… but if the title is weak, nobody clicks.
A simple trick?
Use AI tools to generate ideas like:
- “Top 10 Exclusive Travel Destinations for the Ultra Rich”
- “Inside Billionaire Homes You Won’t Believe Exist”
- “How The Rich Travel Differently (Luxury Secrets)”
The goal is simple:
👉 Make people curious enough to click.
💬 Let’s test this…
Which title would YOU click first?
A. “Top 10 Travel Destinations”
B. “Top 10 Travel Destinations Only Billionaires Can Afford”
Be honest 😄
Step 3: Turn That Idea Into a Full Video (Fast)
Now comes the execution.
Once you have your title:
- Choose a video format (like “YouTube explainer”)
- Set your video length (8–10 minutes works well)
- Select voice style, music, subtitles
- Generate the video
- Make small edits if needed
- Export directly to your phone
That’s it.
No camera.
No mic.
No complex editing.
Just idea → video → upload.
Let’s Talk Realistically…
Is this “push button, get rich”?
No.
But is it a LOT easier than starting from scratch the old way?
100%.
The real difference is consistency.
Most people will:
- Watch this
- Get excited
- Do nothing
A few people will:
- Pick a niche
- Post consistently
- Learn what works
And those are the ones who start seeing results.
Let’s Open This Up…
I want this to be interactive 👇
- Have you ever considered starting a faceless YouTube channel before?
- What’s stopping you right now? (Time? Knowledge? Belief?)
- If you were to start today, what niche would you choose?
Don’t just read and scroll…
Drop your thoughts below - let’s actually discuss this.
A few years ago, if you wanted a new phone, laptop, TV, or even a refrigerator, you had only two options:
👉 Save up until you could afford it.
👉 Borrow money from family, friends, or a bank.
But these days, many Nigerians are using something called Buy Now, Pay Later (BNPL). Instead of paying the full amount upfront, you get the product immediately and spread the payment over several months.
Sounds convenient, right?
But is it actually a smart financial move?
Let's talk about it.
What Exactly Is Buy Now, Pay Later (BNPL)?
Think of it this way:
You see a laptop selling for ₦500,000.
Instead of paying the entire ₦500,000 today, a BNPL provider may allow you to make an initial payment and then spread the balance over several instalments.
So you walk away with the laptop today while paying gradually over time.
For many people, especially entrepreneurs, students, remote workers, and side hustlers, that flexibility can be a lifesaver.
Why More Nigerians Are Using BNPL
Let's be honest...
The prices of phones, laptops, generators, and home appliances have gone through the roof.
A decent laptop can easily cost hundreds of thousands of naira.
Many people simply don't have that amount sitting in their account at once.
BNPL helps because:
✅ You don't need the full amount immediately.
✅ Expensive purchases become easier to manage.
✅ You can get important tools for work or business faster.
✅ Applications are usually done online without lengthy bank processes.
Popular Buy Now, Pay Later Platforms In Nigeria
The article highlighted some of the most popular options Nigerians currently use:
1️⃣ Carbon Zero
Popular for smartphones, gadgets, and electronics.
Depending on the product and your eligibility, you may pay an initial amount and spread the remaining balance over time.
One of the best-known BNPL platforms in Nigeria.
It allows eligible users to shop from participating merchants and pay gradually instead of paying everything upfront.
3️⃣ CDcare
Focused heavily on electronics and household appliances.
Good for people looking to buy TVs, refrigerators, smartphones, laptops, and similar products while spreading payments over time.
4️⃣ Carbon
Many people know Carbon for loans and financial services, but it also offers financing options that can help customers manage purchases through credit products.
What Can You Buy With BNPL?
Depending on the provider, you may be able to finance:
📱 Smartphones
💻 Laptops
📺 Televisions
🧺 Washing machines
❄️ Refrigerators
🪑 Furniture
⚡ Generators and power solutions
🏠 Household appliances
And sometimes even selected services.
How BNPL Usually Works
The process is generally simple:
- Pick the item you want.
- Choose a BNPL payment option.
- Complete the eligibility checks.
- Pay any required upfront deposit.
- Receive your product.
- Repay according to the agreed schedule.
Here's The Part Many People Ignore...
Monthly payments can look attractive.
Very attractive.
You see:
"Pay just ₦45,000 monthly."
And suddenly the purchase feels affordable.
But here's the real question:
How Much Will You Pay In Total?
Before accepting any BNPL offer, check:
✅ Total repayment amount
✅ Interest rate
✅ Processing fees
✅ Down payment requirements
✅ Repayment duration
✅ Late-payment penalties
✅ Refund and cancellation policies
Some repayment plans can end up costing significantly more than the item's cash price.
BNPL Is NOT Free Money
This is where many people get into trouble.
Just because a platform approves you for ₦500,000 doesn't mean you should spend ₦500,000.
A lot of people end up financing things they don't truly need and then struggle with repayments later.
A good rule:
👉 Finance assets that help you earn more money.
👉 Be cautious about financing liabilities that only satisfy short-term desires.
My Biggest Takeaway
BNPL can be amazing when used responsibly.
For example:
- Buying a laptop needed for remote work.
- Getting a phone required for your business.
- Replacing an essential home appliance.
But financing a luxury item just because the monthly payment looks small?
That can become expensive very quickly.
💬 Let's Discuss...
Be honest:
Have you ever used Buy Now, Pay Later before?
- Which platform did you use?
- Was the experience smooth or frustrating?
- Did the repayment plan help you or become a burden?
- Would you rather save up first or pay in instalments?
And here's the controversial question:
Is BNPL a smart financial tool... or just a more attractive way of getting people into debt? 👀
Drop your experience below.👇🏾
Sometimes a win doesn’t look huge.
Sometimes it’s simply realizing you’ve made progress, that possibilities lie ahead, and that you know your next step.
Instead of focusing on what’s wrong or what you don’t have, ask yourself:
What’s going right?
What can I celebrate today?
What do I need, and what can I do next?
Progress.
Possibilities.
And a next step toward the life I love.
I’m grateful the right people are coming into my life at the right time. 💛
Grateful for today. 💛
A few days ago, someone shared a story that got my attention.
They received a call from a person claiming to be from OPay customer care.
The caller sounded professional. He spoke confidently and even seemed to know a few details about the account.
Then he said there was a problem with the account and that an OTP would be sent to "verify" the account.
All they needed to do was read the code back to him.
Sounds harmless, right?
Except it was a scam.
Thankfully, the person became suspicious and ended the call before sharing anything.
But it got me thinking...
How many people would have fallen for it?
With millions of Nigerians now using OPay for transfers, airtime purchases, bill payments, savings, and business transactions, scammers are working overtime to find new ways to trick unsuspecting users.
The scary part?
Most people don't lose money because OPay itself is insecure.
They lose money because scammers know exactly how to manipulate human beings.
So I decided to put together some of the most common OPay scams currently happening in Nigeria and, more importantly, how to protect yourself from them.
1. Fake Customer Care Scam
This is probably the most common OPay scam right now.
Fraudsters pretend to be OPay customer support representatives and contact victims through:
📞 Phone calls
📱 Telegram
🌐 Fake websites
They usually claim there is an issue with your account and ask for sensitive information like:
• OTP codes
• Transaction PIN
• Passwords
• Debit card details
The moment you provide those details, your account could be compromised.
How to Protect Yourself
✅ Never share your OTP with anyone.
✅ Never reveal your transaction PIN.
✅ Contact OPay only through official channels.
✅ Ignore anyone requesting sensitive account information.
2. Fake Credit Alert Scam
If you run a business or sell products online, you've probably heard stories about this one.
A scammer sends a fake payment alert, fake SMS, or screenshot showing that payment has supposedly been made.
Then they pressure the seller to release goods quickly.
Later, the seller discovers that no money actually entered the account.
How to Protect Yourself
✅ Check your actual OPay balance.
✅ Don't rely on screenshots.
✅ Don't rely solely on SMS alerts.
✅ Confirm payment directly inside the OPay app before releasing goods.
3. Phishing Link Scam
You receive a message saying:
"Your OPay account will be suspended."
"Verify your account now."
"Upgrade your account immediately."
The message contains a link.
You click it.
The website looks exactly like OPay.
You enter your details.
And just like that, scammers have your login information.
How to Protect Yourself
✅ Never click suspicious links.
✅ Type official website addresses manually.
✅ Update account information only through the official OPay app.
4. Investment and Giveaway Scams
We've all seen them.
"Invest ₦10,000 and get ₦50,000 tomorrow."
"Congratulations! You've won an OPay giveaway."
"Double your money instantly."
Most of these offers are designed to separate people from their money.
How to Protect Yourself
✅ If it sounds too good to be true, be careful.
✅ Verify promotions through official OPay channels.
✅ Never pay money to claim a prize.
5. QR Code Scam
This scam is becoming increasingly common.
Fraudsters create fake QR codes that redirect payments into their own accounts.
Many people simply scan without checking where the payment is going.
How to Protect Yourself
✅ Confirm recipient details before paying.
✅ Verify the merchant's identity.
✅ Avoid scanning QR codes from unknown sources.
6. Account Upgrade Scam
Scammers may contact you claiming your account requires urgent verification or upgrading.
They'll then ask for:
• BVN
• OTP
• PIN
• Personal account information
That's a major red flag.
How to Protect Yourself
✅ Upgrade your account only inside the OPay app.
✅ Never provide security details through calls, messages, or social media.
7. POS Agent Fraud
Not every POS operator is honest.
Some may:
• Overcharge customers
• Process unauthorized transactions
• Ask you to enter your PIN multiple times
How to Protect Yourself
✅ Use trusted POS agents.
✅ Always collect your receipt.
✅ Check your transaction history immediately after payment.
8. Social Media Impersonation Scam
Scammers now create fake OPay pages on Facebook, Instagram, TikTok, and X.
Many users mistake these pages for official support channels.
How to Protect Yourself
✅ Follow only verified OPay accounts.
✅ Report fake accounts immediately.
✅ Avoid discussing sensitive account issues publicly.
Simple Habits That Can Save You a Lot of Money
Here are some basic security habits every OPay user should adopt:
✅ Enable the new OPay Safety PIN.
✅ Activate biometric login if available.
✅ Use a strong transaction PIN.
✅ Never share your OTP.
✅ Keep your OPay app updated.
✅ Monitor your transaction history regularly.
✅ Avoid public Wi-Fi for financial transactions.
✅ Log out when using shared devices.
✅ Report suspicious activities immediately.
What Should You Do If You Suspect Fraud?
If you think you've been targeted, act immediately:
1️⃣ Freeze your account if possible.
2️⃣ Change your transaction PIN.
3️⃣ Contact OPay customer support.
4️⃣ Notify your linked bank.
5️⃣ Report the incident to the appropriate authorities if money has been stolen.
The faster you respond, the better your chances of reducing the damage.
Final Thoughts
One thing I've noticed is that most scammers aren't hacking systems.
They're hacking trust.
They're counting on people being distracted, scared, excited, or in a hurry.
That's why awareness is your strongest defense.
A few extra seconds of caution can save you from losing thousands - or even hundreds of thousands - of naira.
👇 Now let's hear from the community...
Have you ever encountered an OPay scam attempt before?
What happened?
Was it a fake customer care call?
A fake credit alert?
A suspicious link?
A POS issue?
Or something completely different?
Share your experience in the comments. Your story might help someone else avoid becoming the next victim.
Let me be honest with you…
There are only 2 types of people in this space right now:
- People who are quietly cashing out every week
- People who are still “researching”, watching, and hoping things will click someday
And the painful part?
Most people don’t even realize WHY they’re stuck.
A few days ago, I came across something that made me pause…
Not because it was “new”
But because of how simple and repeatable it actually is.
No hype.
Just a system.
Here’s what shocked me 👇
There are people in Nigeria right now:
- Making ₦100k - ₦500k weekly
- Using just their phone
- Without running ads
- Without having thousands of followers
- Some don’t even show their face
And before you say “it’s not real”…
That’s exactly what I thought too.
But when I looked deeper, I noticed a pattern…
It’s not luck.
It’s not connections.
It’s not “special grace”.
It’s a simple 3-step system:
👉 Step 1: Get attention (without dancing or doing nonsense)
👉 Step 2: Turn that attention into people messaging you
👉 Step 3: Let a system handle the selling
That’s it.
No complicated funnels.
No tech headache.
No “guru grammar”.
Now here’s where it gets interesting…
Most people FAIL at step 1.
Because they think:
- “I need followers first”
- “I need to show my face”
- “I need to run ads”
All wrong.
What I saw inside this was different…
There are templates already working RIGHT NOW
People are literally copying and getting results within days.
Not months.
Days.
Even crazier…
Some of them started making money within:
- 3 days
- 1 week
- While still learning
Let me ask you something…
If someone showed you:
- What to post
- How to get people to message you
- What to say to convert them
- And how to automate everything
Would you still be stuck?
Because that’s really the difference.
Not motivation.
Not hard work.
Just knowing what actually works.
I’m not even going to explain everything here…
Because if I do, you’ll still overthink it and not take action.
Instead…
Go and see it yourself.
But don’t just skim.
Read it like your next income depends on it.
👉Visit here to check it out...
⚠️ But let me warn you…
If you open that page with a “this won’t work” mindset…
You’ll miss everything.
And if you ignore it completely…
There’s a high chance you’ll still be in the same position months from now…
Watching others post wins
While you’re still “trying to understand”
Your choice.
Your title is your promise. It’s what makes a viewer stop scrolling and want more.
If your title isn’t strong, it doesn’t matter how good the video is — no one will watch it.
This lesson is all about planning your title before creating your content.
Why? Because when the title is right, everything else falls into place.
Let’s talk:
- What title idea did you come up with today?
- Did it help clarify your video’s angle or structure?
- What kind of emotion or curiosity does it trigger?
🧠 Tip: Strong titles lead to strong scripts and stronger thumbnails.
🔄 Back to Lesson:
Need to revisit the title checklist? → Click here to return to the lesson.
What it is:
This is a beginner-friendly script writing template designed to help YouTubers plan and organize their video content. Whether you’re creating tutorials, reviews, vlogs, or listicles, having a script keeps your delivery clear, confident, and on track.
What’s Inside:
- Hook Section: Grab your viewer’s attention within the first 5–10 seconds.
- Intro Section: Introduce yourself and quickly explain what the video is about.
- Main Content Framework: Structured prompts for step-by-step delivery, bullet points, and transitions.
- Call-to-Action Section: Remind viewers to like, comment, and subscribe.
- Outro Template: Wrap up your video and direct people to your next content.
Why You Should Use It:
Creating videos without a script often leads to rambling, awkward pauses, or missed points. This template helps you:
- Stay focused
- Improve audience retention
- Sound more professional and confident
- Reduce editing time
